Freightonomics 101 Series
Freight moves on prices. A carrier’s margin is the gap between the rate it charges a shipper and the cost of the diesel, labor, equipment, and insurance it takes to move the load. When inflation runs hot, that gap gets squeezed from both sides at once, and understanding why requires going back to what a “price” actually is before working up to what “inflation” is, what the government measures to track it, and what the Federal Reserve does about it. That is the path this article takes: price, to price index, to GDP, to the money supply, and finally back to freight.
A price is an exchange rate
Strip a price down to its mechanics and it is nothing more than an exchange rate between money and a specific good or service: the number of dollars that changes hands per unit of whatever is received. For a single transaction, this is just money paid divided by quantity received, dollars per gallon of diesel, dollars per truckload, dollars per hour of a driver’s time. Framed this way, a price says nothing about money’s value in any absolute sense. It only says how many units of a good a given quantity of money currently buys, relative to how many it bought a moment ago. If the exchange rate shifts, that could mean the good has become scarcer or more desirable, or it could mean the money side of the ratio changed instead. A single price, on its own, cannot tell you which.
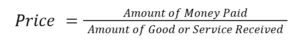
Movements in the parts
Consider what happens when one or parts of the equation changes. Let us say a shipper must get his cereal to the stores, but a market turn has created a budget crunch, decreasing the amount of money available to our shipper to pay for hauling his product. The business’ wants have not changed, but the ability to cover them has. When this happens, he would likely be willing to pay less for the same transport as before, because the budget must stretch to cover all the cereal. This means the price offered decreases, and vice versa when the budget increases: the shipper may not necessarily need to pay more in a given circumstance, but he will be willing to pay more per mile to ensure those boxes of grainy goodness get to the shelves on time.
The same dynamic holds when the budget is held constant and the amount of the good available changes: fewer goods to move means less freight for the shipping budget to cover, relatively speaking, which means a higher price might be offered to ensure what’s there gets to where it needs to go.
While there are many things that will impact either the amount of a given good available or the amount of money available to pay for a unit of said good, at the end of the day, price is a function of the relationship between the two. This correlates with the broader economic concepts of supply and demand, moving from the interaction of an individual transaction to all transactions within a market. Inflation is a similar scaling, covering not just one market, but all markets in an economy.
From one price to a price index
Inflation is what happens when that exchange rate moves in the same direction, upward, for most goods and services simultaneously, rather than for one item in isolation. Because no single good’s price can stand in for “the economy,” statistical agencies build price indices: baskets of goods and services, tracked over time, that approximate how the general exchange rate between money and output is shifting. Three indices do most of the work in U.S. economic reporting. The Bureau of Labor Statistics (BLS) publishes the Consumer Price Index (CPI) monthly, covering prices “paid for consumption by urban households” collected from roughly 75 urban areas and about 23,000 retail and service establishments across the country, and the index anchors cost-of-living adjustments that touch more than 108 million people. BLS also publishes the Producer Price Index (PPI), which measures “the average change over time in the selling prices received by domestic producers for their output,” priced at the first commercial transaction rather than at the register; because producer costs often work their way into consumer prices with a lag, PPI is watched as a leading signal for where CPI may be headed. The third index, the Personal Consumption Expenditures (PCE) price index, comes from the Bureau of Economic Analysis (BEA) rather than BLS, sits inside the same national accounts used to calculate GDP, and has a “core” version that excludes food and energy prices to strip out some of their short-term noise. That last detail matters later, because the PCE price index, not CPI, is the gauge the Federal Reserve has chosen for its own inflation target.
Walking up to GDP
Price indices handle the price side of the exchange-rate equation for a basket of goods; GDP is what happens when the quantity side is scaled up the same way. The BEA defines gross domestic product as “the value of the final goods and services produced” within the country over a period, and it is released quarterly in three successive vintages, advance, second, and third, as more complete source data comes in. Conceptually, GDP substitutes an entire economy’s worth of final output for the single good or service in the basic price equation: nominal GDP is the total money that changed hands for that aggregated bundle, and real GDP backs out the effect of price changes to leave the quantity of output on its own. The ratio connecting the two, nominal GDP divided by real GDP, is the GDP price deflator, which plays the same role for the whole economy that a single item’s price plays in an individual transaction. It is a cousin of the PCE price index from the previous paragraph rather than the same series, since the deflator covers everything the country produces, while PCE covers only what households buy, but both are built on the identical logic of comparing the money paid to the goods and services received. The main point is that the amount of goods and services must be considered in aggregate when one talks about inflation, and GDP is a convenient way to consider production at that scale.
Money itself: M1, M2, and a warning
Lastly, money itself must be considered. When a person has more money in his/her pocket, the person becomes willing to pay a higher price to satisfy a given want. This scales to the economy by looking at the overall supply of money available, and the Federal Reserve tracks it through monetary aggregates published in the H.6 statistical release. M1 consists of currency held by the public plus transaction deposits at depository institutions. Think of it as “liquid,” easily accessible money. M2 is broader, adding small-denomination time deposits and retail money market mutual fund shares to M1.
Now, all three parts of the ratio are there. It should be noted here that the ratio serves to show impact and direction: it cannot be used to directly or mathematically calculate inflation. Admittedly, the world would be easier and more sensible if it could, but that’s a discussion for another day. Assuming the measuring methods stay constant, one can reasonably infer the movements of prices based on changes to the money supply or GDP. Unfortunately, the measures do not stay constant.
Case in point: on April 24, 2020, the Federal Reserve Board amended Regulation D to eliminate the six-per-month transfer limit that had previously distinguished savings deposits from fully liquid transaction accounts. With that regulatory line erased, savings deposits were reclassified as a component of M1 beginning with the May 2020 data. The Federal Reserve’s own technical notes on the H.6 release state that this reclassification would cause “a series break in the M1 monetary aggregate,” adding to M1 “the size of the industry total of savings deposits, which amounted to approximately $11.2 trillion.” In practical terms, headline M1 roughly tripled in a single month, from around $5 trillion to around $16 trillion, purely as a matter of definition, with no new money actually created, as the St. Louis Fed’s FRED Blog later laid out in detail. Anyone reading the M1 series without accounting for that break would see the money supply appear to triple overnight and could badly overstate how much monetary fuel was actually added to the economy, since the dollars in question were already sitting in savings accounts, and were already counted in M2, both before and after the reclassification. M2, which was unaffected by the definitional change, is the more reliable of the two aggregates for judging genuine money-supply-driven inflation risk across that period.
Even a cleanly measured money supply, though, does not translate mechanically into inflation, and the post-COVID episode itself illustrates why. Economists Diego Comin and Robert C. Johnson, in a Brookings Institution paper on supply chains and inflation, model the 2021-2022 surge as two forces compounding each other, expansionary monetary policy pushing up demand, and supply chains too capacity-constrained to expand output to meet it, rather than either acting alone. They estimate binding capacity constraints alone accounted for roughly half of the abnormal post-COVID inflation, since the same rise in demand would have caused far less inflation had supply chains had normal slack to absorb it. At the same time, they find that monetary policy shocks, interacting with that tight capacity, drove the 2021 surge itself, adding roughly four percentage points to inflation that year and outweighing fiscal stimulus from the American Rescue Plan, which played only a secondary role; monetary policy, in their assessment, was the most important force behind both the surge and its retreat once the Fed tightened in 2022. The lesson is not that money creation was irrelevant, but that how much inflation a given monetary or demand shock produces is state-dependent on whether supply chains have room to respond, a factor that no monetary aggregate, correctly measured or not, captures on its own.
Bringing it together: inflation, energy, and the freight market
For a logistics company, inflation is the simultaneous rise, across most of what it buys and sells, in the price ratios discussed above: diesel, equipment, warehouse and terminal space, labor, insurance, and the freight rates carriers charge shippers. Energy carries outsized influence in that mix, because it is both a direct cost, fuel, and an input into nearly every other cost a shipment incurs, from refrigeration to drayage to warehouse power. The U.S. Energy Information Administration (EIA) attributes roughly half of the retail diesel price to crude oil acquisition costs alone, with refining, distribution and marketing, and taxes making up the rest, and it notes that supply disruptions or refinery problems can push prices up quickly when inventories tighten. Carriers pass diesel volatility through to shippers via fuel surcharges, though the EIA is explicit that it does not set or regulate these surcharges; every carrier uses its own formula, typically benchmarked to EIA’s published retail diesel prices.
That outsized sensitivity to energy is also why headline inflation figures can understate what a fuel-intensive industry like freight actually experiences. In the CPI report for the twelve months ending July 2026, the all-items index rose 3.4 percent, core CPI (excluding food and energy) rose 2.5 percent, the energy index rose 14.7 percent, and gasoline specifically rose 24.6 percent. Yet motor fuel, gasoline and other motor fuels combined, carries only about 2.98 percent of the weight in the CPI-U basket. A move that large in one input barely nudges the aggregate index, precisely because the aggregate is a weighted average across an entire consumption basket that most households do not spend nearly as much of on diesel as a trucking fleet does. The result is a real gap between what the topline inflation print says and what a logistics operator’s cost structure actually feels: a sector’s own price exposure can run far hotter, or far cooler, than the economy-wide number that gets the headlines.
Underneath both the topline number and the sector-specific pain sits the Federal Reserve’s inflation target. The Fed aims for 2 percent inflation, measured on the PCE price index, over the longer run, on the reasoning that low and stable inflation lets households and businesses plan their saving, borrowing, and investment decisions with more confidence. As of the July 29, 2026 FOMC statement, the target range for the federal funds rate stood at 3-1/2 to 3-3/4 percent, with the Committee describing inflation as “elevated relative to the Committee’s 2 percent goal.” The Fed’s primary lever for closing that gap is open market operations: buying and selling securities to push the federal funds rate, the overnight rate banks charge each other, toward the FOMC’s target, supplemented by tools such as interest paid on reserve balances, reserve requirements, and, in periods of severe stress, outright large-scale purchases or sales of longer-term securities. Raising the target rate makes borrowing more expensive, which is meant to cool spending, including the spending that finances new trucks, trailers, and warehouse space, and to pull inflation back toward target; cutting the rate does the reverse. Because freight demand tracks the broader cycle of retail sales, housing, and industrial production, the same rate decisions the Fed makes to manage inflation ripple into freight volumes and rates on their own lag, feeding back into the very price ratios this article started with. Inflation, in the end, is not a single number logistics operators can read off a headline. It is the sum of many individual exchange rates between money and specific goods and services, some barely moving, some like fuel moving a great deal, and understanding which-is-which is what separates a useful read on cost exposure from a misleading one.